

Fidelity Investments
by Fidelity Investments
4.1
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.1
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
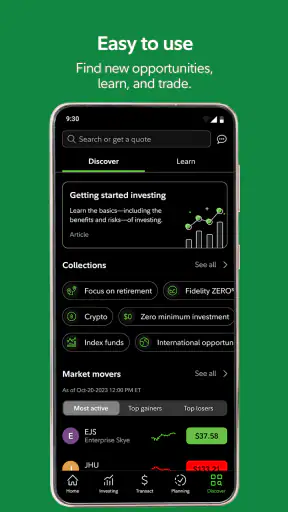
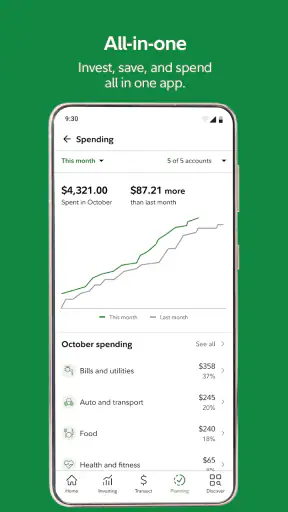
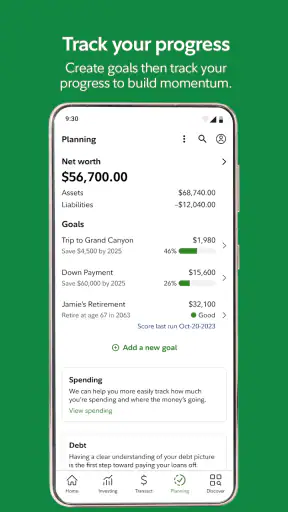
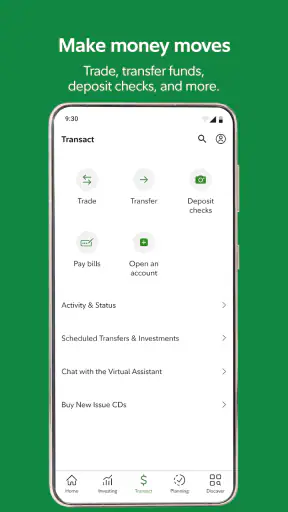
 Analysis by Getfullapps
I usually judge a finance app less by its first impression than by what happens after the first few weeks. Moving money or checking an investment balance can feel useful on day one, but the real question is whether the app still helps when the novelty has disappeared and financial tasks become routine. Fidelity Investments makes a strong early case because it brings investing, saving, and planning into one place, while still leaving enough room for a more deliberate approach than a simple spending tracker.
Developed by Fidelity Investments, this free finance app is aimed at people who want to manage their financial life from a phone rather than split everything between separate banking, investing, and planning tools. It is available for Everyone, has been around since December 15, 2010, and its current version is 4.37. That long presence matters to me: this is not a newly launched experiment that still needs to prove whether it belongs in a regular money routine.
The app has built a substantial audience, with over 5 million installs, an average rating of 4.1, and hundreds of thousands of ratings. Those figures suggest broad usefulness, but they do not guarantee that every user will enjoy the same workflow. Fidelity is most convincing when I want a central place for long-term financial decisions. It is less compelling if my only need is a lightweight daily expense log or a very simple savings dashboard.
From first-week appeal to lasting financial habit
I find that an app’s real value shows up after the first-week curiosity fades, when I’m deciding whether it can support a habit without demanding constant attention. In this section, I look at how Fidelity can turn occasional account checks into a steady review routine, and where its broader approach may be more than some people need.
Why the first few sessions feel worthwhile
The immediate appeal is concentration. Instead of treating investing, saving, and planning as unrelated chores, Fidelity presents them as parts of one financial picture. I find that helpful because it encourages me to connect a short-term action with a longer-term purpose. Checking an account is no longer just looking at a number; it can become a prompt to think about whether my current choices support the goal I set for myself.
That does not mean the app removes the need to understand what I am doing. Finance apps can make a transaction feel deceptively easy, especially when a few taps separate a user from an investment decision. My preferred approach is to use the first week for orientation rather than immediately changing everything. I would review the available account information, look at the planning areas, and decide which parts deserve regular attention.
A realistic everyday scenario is a user who receives income, pays regular bills elsewhere, and wants to make a monthly contribution to a long-term account. Fidelity can serve as the place to check progress, review the effect of that contribution, and keep the broader objective visible. The benefit is not excitement; it is reducing the number of places I need to remember when I want to make a considered financial check-in.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
For someone new to investing, that central view can be reassuring, but it should not be confused with personal advice. I would still read each screen carefully and avoid treating a suggested action as automatically appropriate. The app is useful as an organizing tool and research companion, yet the responsibility for risk, time horizon, and affordability remains with me.
What makes it different from simpler alternatives
A basic budgeting app usually focuses on spending categories, cash flow, or reminders. A standalone investing app may concentrate on buying and monitoring investments with a simpler interface. Fidelity Investments sits closer to a broad financial workspace. Its advantage is the connection between saving, investing, and planning, particularly for users who dislike maintaining several separate financial routines.
That breadth is also the first trade-off. A focused budgeting app may be easier to understand when I only want to see where my money went this week. A specialized investing tool may feel cleaner when I want a narrow, market-oriented experience. Fidelity is better suited to someone who values consolidation over minimalism.
I would recommend giving the app a specific job during the first week. For example, I might use it to establish a monthly review habit, check whether my saving activity matches a longer-term plan, and record questions to investigate before making a decision. That is more useful than opening it repeatedly without a purpose. A finance app earns a place on my phone when it changes behavior, not merely when it displays information attractively.
The details that matter when choosing it
The app is free, which lowers the barrier to trying it and makes it practical for a user who wants to explore a broader financial dashboard without paying for the app itself. Free access should not be interpreted as a reason to make hurried decisions, though. Investing always involves choices that deserve more attention than the download price.
The Everyone age rating also makes the app broadly accessible from a content-rating perspective. In practice, suitability depends far more on financial experience and personal circumstances than on age classification. A first-time investor may need to slow down and learn the terminology, while an experienced user may mainly care about speed, clarity, and whether the app fits an established routine.
Month-to-month value comes from repetition
After the first month, the strongest reason to keep Fidelity installed is the possibility of a repeatable review cycle. I can return at a chosen point in the month, compare my progress with the goals I am tracking, and decide whether anything actually needs action. This is a healthier pattern than checking balances several times a day, especially when market movement could encourage emotional reactions.
One useful habit is to separate observation from action. During a routine check, I would first review what changed, then ask whether the change affects my plan, and only afterward consider whether I need to do anything. That small pause is important. It prevents the app from turning every fluctuation into a reason to trade or constantly adjust a long-term strategy.
The planning side becomes more valuable when I connect it to a real calendar event. A yearly insurance payment, a planned move, education costs, or a future reduction in working hours can give a financial dashboard a concrete purpose. Rather than treating planning as a one-time setup task, I would revisit assumptions when my income, household, or priorities change.
Another non-obvious strength is that consolidation can improve follow-through even when it does not provide more information than separate services. Every additional account, login, and app creates a small chance that I will postpone a review. Keeping related financial tasks together can make the recurring action easier to remember. For me, that is a maintenance advantage rather than a flashy feature.
Where the monthly routine can become tiring
The same breadth that helps with organization can create cognitive load. A user may open the app intending to perform one simple task and end up moving through several account views, planning prompts, or investment details. If I only have a minute to check something, a broad financial environment may feel heavier than a focused tool.
There is also a psychological burden in seeing long-term financial information frequently. A person who is prone to checking market changes may find that easy access increases worry instead of improving discipline. In that situation, the best use of the app may involve fewer, scheduled visits rather than constant monitoring. An app cannot create calm by itself; the user has to set boundaries around the habit.
I would also avoid measuring its value by how many screens I use. Some people will benefit from the planning perspective while barely touching other areas. That is perfectly reasonable. The app does not need to become the center of every financial decision to be worthwhile. It only needs to make an important recurring task clearer or easier.
Maintenance: light for organized users, heavier for everyone else
Fidelity is easiest to maintain when I already know what I want from it. If my goals are vague, the app can become another place where I collect financial information without turning it into a plan. Before relying on it, I would define a small number of recurring questions: Am I saving consistently? Is my investment approach still appropriate for my time horizon? Has a change in my life made the old plan less suitable?
That approach keeps maintenance intentional. I do not need to inspect every available area every time I open the app. A monthly review can focus on progress and upcoming decisions, while a less frequent planning review can address larger changes. The exact schedule should match the user’s circumstances, but the principle is the same: use the app as a prompt for decisions, not as a demand for continuous attention.
Keeping software current is part of normal maintenance too. The current version is 4.37, so I would use the normal update process on my device and check that the app remains comfortable to navigate after updates. I would also protect access to the phone and account because a finance app deserves more care than an ordinary entertainment download. Convenience is valuable only when paired with sensible security habits.
A practical tip is to write down the reason for each recurring review before opening the app. “Check whether I am on track for my goal” is more useful than “look at my investments.” The first wording encourages a decision; the second can lead to aimless scrolling. This small distinction helps the app support a habit instead of becoming a source of distraction.
When the app becomes fatiguing
The main source of fatigue is not necessarily a missing function. It is the emotional weight of managing money in a single place. Seeing saving, investing, and planning together can make financial responsibilities feel more immediate. For a user who already feels overwhelmed, a simpler tool with a narrower purpose may be kinder and easier to sustain.
Another point of friction is the gap between convenience and understanding. A smooth mobile workflow can encourage confidence before the user has fully understood an investment choice. I would never use the app’s ease of navigation as evidence that a decision is low risk. The best long-term experience comes from pairing the app with independent learning and a written personal plan.
Market-focused users may also find the broader approach less satisfying than a specialized platform designed around rapid monitoring or advanced analysis. Fidelity makes more sense to me when I want a durable financial routine than when I want an intense, constantly changing trading workspace. If speed, deep market tools, or a very stripped-down interface is the priority, another category of app may fit better.
There is a similar trade-off for people who only want expense tracking. Fidelity can be excessive if the central problem is understanding everyday spending. A dedicated budgeting app may provide a clearer picture of categories and cash flow with less financial information competing for attention. I would choose Fidelity when the investment and planning side matters, not simply because it is free.
Who should keep it installed
I think this app is a good match for someone building a long-term money routine and wanting related financial tasks in one mobile environment. It is especially suitable for a user who prefers reviewing progress calmly, values a connection between saving and investing, and is willing to learn enough to make informed decisions.
It can also suit a busy person who repeatedly postpones financial maintenance because the information is scattered. Consolidation may remove enough friction to make a monthly review realistic. The benefit is strongest when the user sets a clear purpose and returns on a schedule.
I would hesitate to recommend it as the only financial tool for a person whose main need is detailed household budgeting, as well as for someone seeking a highly specialized trading interface. It is also not a shortcut for financial education. A beginner can use it, but should treat the early sessions as orientation and learning rather than a race to act.
My long-term verdict
After the novelty fades, Fidelity Investments earns lasting space when I use it as a disciplined checkpoint rather than an always-open stream of financial stimulation. Its lasting value comes from bringing investing, saving, and planning into a shared routine, making it easier to connect individual actions with broader goals.
The app’s 4.1 average from a large user base reflects a generally positive reception, but I would read that as evidence of broad usefulness rather than a promise of a perfect experience. The interface and scope may feel reassuring to one person and crowded to another. That difference depends on whether I want a complete financial workspace or a single-purpose tool.
My recommendation is to try it with a defined monthly workflow: review progress, compare it with the goal, note any life changes, and avoid acting simply because the app makes action available. If that routine becomes easier and more consistent, the app is doing something valuable. If it leaves me checking too often, feeling overloaded, or still needing a separate tool for the task I care about most, I would choose a more focused alternative.
The lasting test is simple: Fidelity is worth keeping when it helps me make fewer, clearer, better-timed financial decisions. It is not the right choice for every financial personality, but for users who want one established, free mobile app to support saving, investing, and planning over time, it has a credible place in a long-term routine.
Pros
- User-friendly interface for easy navigation.
- Comprehensive research tools available.
- Customizable alerts for market trends.
- Secure login with biometric authentication.
- Wide range of investment options.
Cons
- Occasional app freezes reported.
- Limited cryptocurrency options.
- Some features require desktop access.
- Can be overwhelming for beginners.
- Notifications can be delayed.
FAQs for Fidelity Investments
What features does the Fidelity Investments app offer?
The Fidelity Investments app provides a comprehensive suite of features for investors. Users can trade stocks, ETFs, and mutual funds directly from their mobile devices. The app also offers real-time quotes, personalized watchlists, and market news. Additionally, users can access their account statements, manage retirement accounts, and use financial planning tools for a holistic investment strategy.
Is the Fidelity Investments app secure?
Yes, security is a top priority for Fidelity Investments. The app uses advanced encryption to protect user data and offers two-factor authentication for additional security. Users can also set up biometric logins, such as fingerprint or facial recognition, to ensure that their accounts remain secure even if their device is lost or stolen.
Does the Fidelity Investments app support international trading?
The Fidelity Investments app primarily supports trading within the U.S. markets. However, it does provide access to certain international markets through American Depositary Receipts (ADRs) and international mutual funds. Users interested in a broader range of international trading options should explore Fidelity's website or contact customer support for more details.
Is there a fee to use the Fidelity Investments app?
Downloading and using the Fidelity Investments app is free. However, users may incur fees associated with trading activities, such as commissions on certain trades or account management fees for specific services. It's advisable to review Fidelity's fee schedule to understand any potential costs associated with trading or account management.
Can I access customer support through the Fidelity Investments app?
Yes, the Fidelity Investments app provides access to customer support. Users can reach out via chat, phone, or email directly from the app. The app also offers a comprehensive FAQ section and educational resources to help users navigate investment decisions and troubleshoot any issues that may arise.

Fidelity Investments
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via ElectronicChannelSupport@fidelity.com, visit https://www.fidelity.com, or review their https://www.fidelity.com/privacy-policy.










